Closing costs are a stack, not a headline
Educational overview. Not individualized financial, legal, or tax advice. How we source and check numbers.
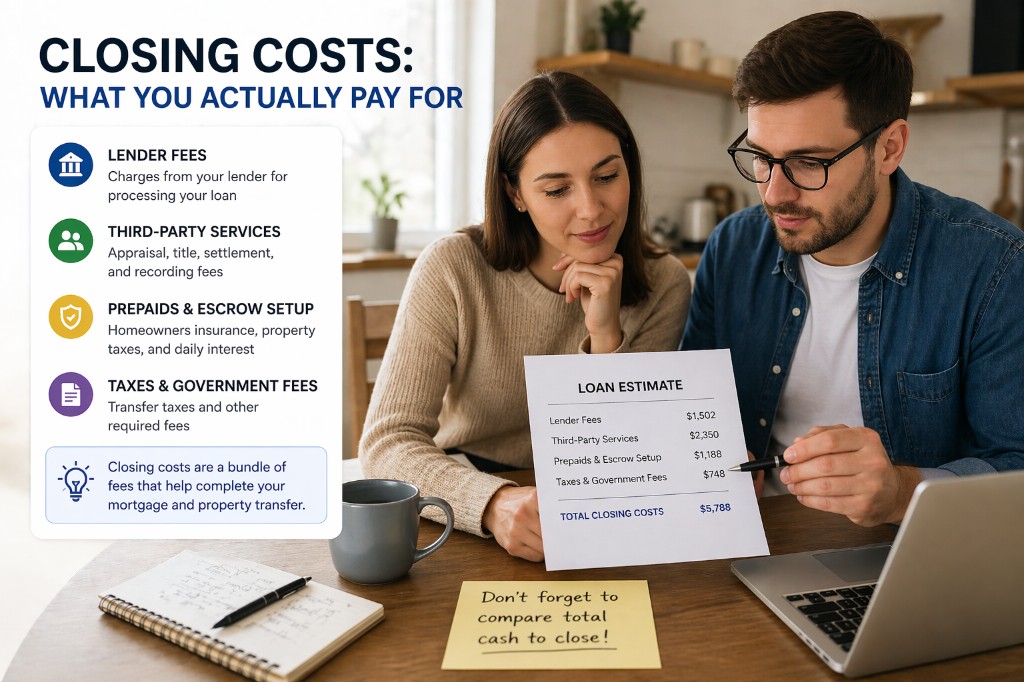
Closing costs are the cash that has to be at the table besides the down payment. They are not one fee. They are a stack of lender charges, title work, government taxes, and prepaid items, and they are the usual reason two Loan Estimates look unrelated even when the rate is close.
The CFPB tells early shoppers to plan on roughly 2 to 5 percent of the purchase price for closing costs, not counting the down payment. That band is a planning range, not a quote. In 2022 the Bureau reported a median of nearly $6,000 in total loan costs on purchase mortgages, and it later noted that those lender-side costs rose more than 36 percent from 2021 to 2023. Title insurance alone often runs about 0.5 to 1 percent of price. Transfer taxes can add nothing in one state and several thousand dollars in another. National averages hide that spread.
What follows is how the stack is built on the official form, what a $400,000 purchase can look like in cash, and how to compare two lenders without mixing lock periods, points, or escrow assumptions. Your state, your closing date, and your insurance quote will move the number. The Loan Estimate is the document to trust, not a website average.
The five buckets on the form
Lenders have to use a standardized Loan Estimate, so the labels are comparable even when the dollars are not. Section A is lender charges: origination, underwriting, and optional discount points. Points are prepaid interest. One point is 1 percent of the loan. Lender credits sit here too, as a negative: you take a higher rate and the lender applies cash toward the rest of the sheet. That is a pricing choice, not a gift.
Section B is third-party work the lender picks, usually the appraisal, the credit report, and sometimes a flood certification. You generally cannot choose those providers. Section C is work you can shop, most often title insurance and the settlement or escrow fee. In many states the buyer can pick the title company. Waiting until the week of closing is how people pay the first quote they are handed. Section E is government: recording, filing, and transfer taxes. Those lines are geography, not lender appetite.
Sections F and G look like fees and are mostly timing. Prepaids include the first year of homeowners insurance, tax installments due at closing, and prepaid interest from the closing day to the end of the month. Closing on the 3rd costs more prepaid interest than closing on the 28th. The initial escrow deposit is a cushion so the servicer can pay the next tax and insurance bills. Two honest lenders can disagree here because they assumed different dates or different insurance premiums. That gap is not one of them being cheaper.
Seller credits and lender credits are easy to confuse and they are not the same thing. A seller credit is negotiated in the purchase contract and applied at settlement, subject to program caps. A lender credit is part of the rate you accepted. Both can lower cash to close. They show up in different places, and both can be limited by the appraisal or the loan program. Rolling costs into the loan is sometimes allowed. On a thin-equity conventional loan, cash is still the usual requirement. A few items may be deductible the year you buy. Many are not. That is a CPA question.
Cash to close on a $400,000 purchase
Suppose the price is $400,000, the down payment is 10 percent ($40,000), and the loan is $360,000. The down payment is not a closing cost, but it is part of the money that has to clear. Using the CFPB planning band of 2 to 5 percent, closing costs alone land roughly between $8,000 and $20,000 before any seller concession. High transfer-tax counties and a large escrow setup can push the top of that range higher. Add the down payment and you are looking at something like $48,000 to $64,000 of verified funds, plus a buffer for last-minute changes. That is why lenders ask for bank statements early. They are checking the down payment and the settlement stack.
| Line | Planning range | What moves it |
|---|---|---|
| Down payment | $40,000 | Your contract and loan program, not a fee. |
| Lender and third-party (A–C) | $4,500 to $8,500 | Origination, points or credits, appraisal, title. |
| Taxes and recording (E) | $500 to $6,000+ | State and city transfer taxes. Wide by county. |
| Prepaids (F) | $2,000 to $5,000 | Insurance, tax installments, prepaid interest. |
| Escrow setup (G) | $2,500 to $5,000 | Often two to six months of tax and insurance. |
First-time buyers get surprised in the same places. They budget the down payment and forget the rest. They chase the lowest rate without netting points and origination. They treat a national “closing cost” widget as if it knew their county. They move money late, without a paper trail, and underwriting stalls even though the cash exists. They skip the Closing Disclosure because it arrived three days before signing, which is exactly when a wrong transfer-tax line is still fixable.
Comparing two estimates without mixing products
Lenders compete on rate, points, and credits in different combinations. One offer is 6.50 percent with no points and ordinary fees. Another is 6.375 percent with one point ($3,600 on a $360,000 loan). A third advertises a rock-bottom rate and recovers it in origination. The fair comparison is not who printed the lowest rate. It is net lender cost on Section A, third-party cost on B and C with the same providers if you can hold them constant, prepaids and escrow only after the closing date and insurance quote match, and cash to close on page 2 for the same loan amount, term, and lock period.
A 15-day lock and a 45-day lock are not the same product. Ask for zero-point pricing from every lender on the same day, then decide points separately against the years you will keep the loan. If the seller agreed to a credit, confirm it appears on the estimate and that the program allows it. Some fees are allowed to change after disclosure. Lender charges are tighter. Prepaid interest always moves if the closing date slips. Three business days before signing you should get a Closing Disclosure. Read it against the latest Loan Estimate. A jump in lender fees without a change you recognize is worth a call before you sit down.
Walk the form itself in how to read a Loan Estimate. If you are lining up price, credits, and financing on more than one house, use the offer comparison tool so you are not holding the stack in your head. Live rate context is on the market page.
Sources: CFPB, typical closing costs 2–5% of price, CFPB 2024 RFI on mortgage fees, CFPB Loan Estimate. Educational only. Not legal or tax advice.